The Great Toy Industry Margin Squeeze: Who Is Actually Making Any Money?
The global toy industry is facing an increasingly uncomfortable financial reality. Manufacturing costs are rising, retailers are demanding competitive prices, promotional expenditure continues to grow, and bringing a new toy to market is becoming more expensive. Meanwhile, American consumers are facing sharply higher toy prices in 2026. Yet despite all this additional money flowing through the system, it isn't necessarily translating into higher profits for toy companies. So where is the money actually going, who is managing to protect their margins, and which businesses are finding themselves squeezed hardest?

The Toy Industry Is Growing, So Why Does Making Money Feel So Difficult?
On the face of it, the toy industry should be feeling reasonably optimistic about 2026. Consumer demand has proved more resilient than many expected, collectibles and trading cards continue to perform strongly, and several major toy manufacturers have reported encouraging sales trends.
According to Circana, US toy industry dollar sales increased by 17% during the first six months of 2026 compared with the same period in 2025, while unit sales increased by 12%. Average selling prices rose by 4%, driven partly by strong demand for trading cards, collectibles and higher-value products. This represented the strongest first-half performance for the American toy market in six years.
However, the positive sales figures conceal a much more complicated situation when it comes to profitability. Revenue growth does not automatically translate into higher profits, particularly when the costs involved in manufacturing, marketing and distributing toys are increasing at the same time.
In October 2026, Reuters reported that US toy prices had increased by 6.6% over the preceding year, including an unusually sharp 4.2% increase in September alone. Tariffs, higher energy costs and increased transportation expenses have all contributed to the pressure on consumer prices.
These two sets of statistics measure different things: Circana tracks retail selling prices and product mix, whereas the inflation figures track price changes in a consumer price index. Nevertheless, together they illustrate an important development. Consumers are paying more for toys, even as manufacturers face a difficult operating environment. The natural assumption might be that higher retail prices mean somebody in the supply chain is making more money. In reality, much of that additional revenue may simply be covering higher costs.
This raises a question that deserves considerably more attention within the toy industry: are we becoming an industry that is increasingly good at generating sales but less effective at converting those sales into sustainable profits?
Manufacturing Costs: The Pressure Begins Long Before Toys Reach the Shelf
The profitability problem often begins at the factory. Over the past several years, toy manufacturers have faced considerable volatility in raw material prices, labour costs, energy expenditure, freight rates and international trade arrangements.
Plastic remains a fundamental material for a substantial proportion of the global toy industry, making manufacturers particularly exposed to changes in petrochemical prices. Higher oil and energy costs can affect not only the cost of plastic resins but also factory operations, packaging production and international transportation.
Labour costs in traditional manufacturing centres have also changed considerably over time. China remains the dominant global toy manufacturing location, supported by an exceptionally sophisticated network of component suppliers, tooling specialists, factories and logistics providers. However, increasing labour costs and continuing geopolitical uncertainty have encouraged many toy companies to investigate alternative manufacturing locations.
India, Vietnam, Indonesia and Mexico are among the countries attracting attention as businesses attempt to diversify their supply chains and reduce their exposure to particular markets. Unfortunately, moving production is rarely as straightforward as obtaining a cheaper factory quotation. Tooling transfers, supplier qualification, quality assurance, production efficiency and logistics costs can quickly erode the savings that initially made a new manufacturing location attractive.
For many toy companies, the result is an awkward balancing act. They need to reduce manufacturing costs to remain competitive, while simultaneously investing additional resources to make their supply chains more resilient.
The US tariff situation has made these decisions even more complicated. The changing tariff arrangements affecting Chinese imports have introduced substantial uncertainty into pricing and sourcing decisions, while the lingering effects of earlier duties continue to influence costs throughout the supply chain.
Importantly, manufacturers cannot always pass these increases directly to their customers. Many retail price points are commercially sensitive, and retailers may resist increases that threaten consumer demand. The outcome is that manufacturers are often caught between factories seeking higher prices and retailers demanding that those prices remain unchanged.
Retailers Want Lower Prices, Consumers Want Better Value, and Somebody Has to Pay
Retailers face their own commercial pressures, of course. Large retail chains must compete aggressively on price, maintain attractive product ranges and manage substantial overheads associated with their stores, staff, distribution networks and increasingly sophisticated online operations.
Nevertheless, the buying power of major retail customers places toy manufacturers in a challenging negotiating position. Retail buyers understandably want products that deliver attractive margins and strong sales performance. They also expect suppliers to contribute towards promotions, marketing campaigns, displays and other activities intended to encourage consumers to purchase their products.
These costs are not necessarily unreasonable. Effective promotional activity can create substantial additional demand and benefit both the retailer and manufacturer. However, the cumulative financial impact can become considerable, particularly when promotional support is combined with lower wholesale prices and increasingly demanding service requirements.
A toy manufacturer might negotiate what appears to be an acceptable selling price, only to discover that the true profitability of the account is significantly reduced by promotional allowances, retailer-specific packaging, freight, compliance expenditure and potential markdown contributions.
One particularly uncomfortable development is the increasing tendency for promotions to become an expected part of the commercial relationship rather than occasional activities designed to generate incremental sales.
Consumers have become accustomed to discounts, special offers and promotional events throughout the year. From Black Friday to major online sales events, the pressure to offer compelling promotional prices can be relentless.
The danger is that products become priced and marketed around an expectation of discounting. If consumers learn that a toy regularly sells for 20% or 30% below its recommended retail price, the original price may gradually lose its credibility.
For manufacturers, supporting those discounts can become expensive. For retailers, the commercial benefits depend on whether additional sales volumes genuinely compensate for the lower margins.
Ultimately, both parties face the same fundamental problem: selling more toys is only commercially worthwhile if the additional sales generate sufficient profit.
The Real Cost of Developing a New Toy Is Increasing
One area of margin pressure that receives comparatively little attention is the growing cost of bringing new products to market.
Developing a successful toy has always required investment in design, engineering, prototyping, tooling, testing, packaging and marketing. However, the commercial environment surrounding product development has become increasingly demanding.
Manufacturers face stringent safety and compliance requirements, particularly when products are being sold across multiple international markets. While these requirements are essential for protecting consumers, they also create costs that manufacturers must recover through product sales.
Complex electronic toys, connected products and products incorporating new technologies can introduce additional engineering, certification and support requirements. Meanwhile, the cost of creating sufficient consumer awareness to launch a new toy successfully can be substantial.
Traditional advertising remains important in certain categories, but digital marketing has introduced its own financial challenges. Social media campaigns, influencer partnerships, online advertising and content creation can all absorb significant budgets without guaranteeing that consumers will actually purchase the products being promoted.
There is also the fundamental risk associated with product development itself. For every successful new toy, there are numerous products that fail to meet their original sales expectations.
A company developing ten new products cannot realistically expect all ten to become commercial successes. The profits generated by the winners must therefore be sufficient to cover not only their own development costs but also the investment made in less successful products.
This is one of the reasons why apparently attractive gross margins can be misleading. A toy that sells for three or four times its factory cost may look extremely profitable, but the factory price is only one part of the commercial equation.
By the time development expenditure, licensing royalties, packaging, freight, warehousing, marketing, retailer contributions and general overheads have been accounted for, the actual operating profit can be surprisingly modest.
As the commercial lifespan of some toy trends becomes shorter, manufacturers may have less time to recover these upfront investments before consumer attention moves elsewhere.
The Licensing Dilemma: Stronger Demand, but Who Gets the Profits?
Licensing is another area where the economics of the toy industry deserve closer examination. Licensed toys have been an important feature of the global toy business for decades, and successful entertainment properties can generate enormous commercial opportunities. A strong licence provides immediate consumer recognition, creates an established emotional connection with the audience and can significantly improve a product's prospects of securing retail distribution.
However, these advantages come at a price.
Toy companies licensing major entertainment properties must typically pay royalties to the intellectual property owner, often alongside minimum guarantees and other contractual commitments. Depending on the agreement, manufacturers may also incur additional costs associated with product approvals, packaging requirements and marketing obligations.
None of this is inherently problematic. An excellent licensing arrangement can be extremely profitable for everyone involved, particularly when a property generates strong consumer demand and substantial sales volumes.
The challenge arises when competition for desirable licences pushes the commercial terms beyond what the underlying toy products can reasonably support. A manufacturer may find itself paying significant royalties while also accepting tight retailer margins and funding substantial marketing activity. If the resulting products sell exceptionally well, the economics can still work. If demand is weaker than expected, the financial consequences can be painful.
There is also the question of who carries the greatest risk. The intellectual property owner may receive a contractual royalty or guarantee, while the toy manufacturer typically assumes responsibility for production, inventory and much of the commercial execution.
This arrangement can work perfectly well when the risks and rewards are appropriately balanced. However, it becomes considerably less attractive when a manufacturer is carrying most of the operational and financial exposure without retaining a sufficient share of the eventual profit.
It is therefore worth asking whether some toy companies have become so focused on securing high-profile licences that they are paying too much for the privilege of manufacturing the resulting products.
Sometimes, developing original intellectual property or concentrating on established owned brands may generate better long-term financial returns than competing for the latest fashionable entertainment licence.
The Numbers Don't Lie: Even the Biggest Toy Companies Are Feeling the Pressure
One of the most revealing aspects of the current market is that margin pressure is not confined to smaller manufacturers. Some of the industry's biggest companies are reporting results that illustrate just how challenging it can be to turn revenue growth into meaningful increases in profit.
Mattel provides a particularly interesting example. During the second quarter of 2026, the company reported a 10% increase in net sales to approximately $1.13 billion. However, its reported gross margin declined from 50.9% to 48.2%, while adjusted operating income fell from $96 million to $39 million. The company identified tariffs, inflation, higher royalties and unfavourable exchange rates among the factors affecting profitability, alongside increased advertising expenditure.
This illustrates the challenge rather neatly. Mattel sold more, yet earned substantially less operating profit during the quarter. Even with the resources, purchasing power and brand portfolio of a global industry leader, protecting margins is far from straightforward.
Spin Master's second-quarter results provide another revealing example, although its performance was more encouraging. The company reported revenue of $436.4 million, representing growth of approximately 9%, while adjusted EBITDA increased to $51.6 million. However, its toy division recorded sales allowances of $53 million, equivalent to 12.8% of gross toy product sales. These allowances included items such as promotional discounts, rebates, markdowns and cooperative advertising.
It is worth considering what that figure means. Before looking at the manufacturer's own marketing, product development and operating expenditure, a substantial proportion of gross toy sales is already being accounted for by commercial arrangements with customers.
Meanwhile, Hasbro's latest results demonstrate that some businesses are finding ways to protect and improve profitability despite challenging conditions. In October 2026, the company reported third-quarter revenue of approximately $1.6 billion, with particularly strong growth from Magic: The Gathering and digital gaming. Its consumer products division also improved its operating performance, although the reported improvement benefited partly from tariff refunds.
The distinction is important. The industry's leading companies are not all experiencing the same financial outcomes, even when operating within broadly similar market conditions.
Successful intellectual property, the right product mix, disciplined expenditure and operational efficiency can make an enormous difference.
Who Is Actually Making Money? The Winners and Losers
There are several areas of the toy business where the underlying economics appear more attractive than others, although success is certainly not guaranteed in any particular category.
The potential winners: Companies with strong owned brands and intellectual property
Businesses that own successful toy brands have an important structural advantage. They can develop products without paying third-party licensing royalties on those properties, control their own brand strategy and potentially generate additional revenue by licensing their intellectual property into other product categories or entertainment formats.
LEGO is a particularly impressive example of the value of combining a strong brand, differentiated products and international scale. The company reportedly increased revenue by 21% and net profit by 32% during the first half of 2026, supported by growth across its product portfolio and successful engagement with adult consumers.
However, owned intellectual property is only valuable when consumers actually want it. Building a successful brand requires substantial long-term investment, and many manufacturers simply do not have the resources or patience necessary to achieve that level of consumer recognition.
The potential winners: Collectibles, trading cards and repeat-purchase products
Trading cards and collectibles have been among the standout performers in the toy industry during 2026. Their commercial appeal goes beyond strong consumer demand; successful collectible ranges can encourage repeat purchasing, support ongoing product releases and create highly engaged communities of consumers.
Hasbro's extraordinary performance with Magic: The Gathering demonstrates the potential of this business model. The company reported more than $600 million in Magic revenue during the third quarter of 2026 alone, with demand supported by new releases and a highly established player community.
Barron's
Obviously, not every collectible toy range will achieve anything approaching this level of success. The category can be highly trend-driven, and unsuccessful products can leave manufacturers with substantial unsold inventory.
Nevertheless, businesses that successfully establish recurring consumer demand can enjoy significant advantages over manufacturers that must continually develop completely new products simply to maintain their existing sales levels.
The potential winners: Efficient, differentiated smaller toy companies
Smaller toy companies are not necessarily disadvantaged by the current environment. In fact, some may be better positioned than larger competitors to exploit specific opportunities, particularly where they have low overheads, strong product differentiation and access to specialist distribution channels.
A company with a small team, outsourced manufacturing and a limited range of successful products may generate an attractive return without needing to achieve enormous annual sales. The key is commercial discipline. Businesses that carefully manage development expenditure, avoid unnecessary inventory commitments and focus on genuinely profitable customers can build sustainable operations even when competing against companies with substantially greater resources.
The businesses facing the greatest pressure: Undifferentiated manufacturers
Manufacturers producing relatively generic toys without meaningful brand recognition or distinctive product features are particularly exposed to margin pressure.
When retailers and consumers perceive little difference between competing products, price becomes an increasingly important factor in purchasing decisions. Manufacturers may find themselves competing primarily on cost, with limited ability to recover increases in manufacturing or transportation expenses.
Businesses operating in highly competitive, price-sensitive product categories therefore face a difficult challenge. They must achieve sufficient operational efficiency to remain commercially attractive while finding ways to differentiate their products from competing alternatives.
The businesses facing the greatest pressure: Overextended toy companies
Another vulnerable group consists of manufacturers that have expanded too aggressively, developing too many products, acquiring expensive licences or making substantial inventory commitments based on optimistic sales forecasts.
These companies may report impressive turnover while struggling with cash flow and profitability. Unsold inventory can become particularly damaging because of its tendency to lose commercial value as consumer trends change or retail seasons pass. The costs associated with clearing obsolete stock can eliminate much of the profit generated by successful products elsewhere in the range.
What About Toy Retailers? Are They Making All the Money?
It is tempting for manufacturers to view retailers as the main beneficiaries of the industry's commercial arrangements. After all, major retail chains possess considerable purchasing power and can exert substantial influence over suppliers. However, retail profitability is not necessarily straightforward either.
Physical retailers face significant costs associated with property, staffing, energy, warehousing, logistics and increasingly complex omnichannel operations. Competition from online retailers and direct-to-consumer brands has also intensified price transparency, making it difficult to maintain attractive margins on products that are widely available elsewhere.
A retailer might achieve a gross margin of 35% or 40% on a particular toy, but that figure does not represent its eventual profit. Operating expenditure must be deducted before the business earns a meaningful return.
Online retail introduces its own challenges. Marketplace commissions, fulfilment expenses, advertising costs and customer returns can absorb a significant proportion of revenue, particularly for lower-priced products.
Nevertheless, major retailers possess an important advantage: they can spread their operating costs across enormous sales volumes and negotiate commercial terms that smaller competitors cannot easily replicate.
The most successful retailers also benefit from sophisticated data analysis, inventory management and pricing systems that help optimise product selection and profitability.
Specialist toy retailers, meanwhile, can sometimes compete effectively by offering experiences, expertise and product ranges that mass-market operators struggle to match.
The lesson is that retailers, like manufacturers, must carefully manage the relationship between revenue, gross margin and operating costs. Large sales volumes do not guarantee attractive profits at either end of the supply chain.
A Simple Example of How Margins Disappear
Consider a hypothetical toy manufacturer selling a product with a retail price of $29.99.
The manufacturer sells the product to a retailer for $15.00 and initially estimates a healthy profit based on a factory cost of $6.00 per unit. However, the actual economics might look rather different once the full range of expenditure is considered.
Cost or income | Per unit |
Wholesale selling price | $15.00 |
Factory production cost | -$6.00 |
Freight, duty and logistics | -$1.50 |
Licensing royalties | -$1.20 |
Retail promotional contributions | -$1.00 |
Product development amortisation | -$0.80 |
Marketing expenditure | -$1.20 |
Contribution before general overheads | $3.30 |
This is an illustrative example rather than an industry average, and individual costs will vary considerably between products and companies. Nevertheless, the commercial point is important. What initially appeared to be $9.00 of gross profit based on the factory cost has been reduced to just $3.30 once additional expenses are considered. That remaining contribution must still help cover salaries, offices, administration, finance costs and other business overheads.
If the retailer subsequently requires additional promotional funding or the manufacturer incurs unexpected freight costs, the remaining profitability can quickly deteriorate.
The danger becomes particularly acute when companies rely on large sales volumes to compensate for narrow margins. A relatively small increase in costs can have a disproportionate impact on operating profit.
This is why toy manufacturers need to understand the profitability of individual products and customers rather than simply concentrating on overall revenue.
Is the Toy Industry Spending Too Much Money Chasing Growth?
An uncomfortable question worth asking is whether some toy companies are contributing to their own profitability problems by pursuing growth without sufficient consideration of the costs involved.
The industry has a longstanding tendency to celebrate increased sales, new retail listings, major licensing agreements and expanding product portfolios. These achievements can certainly indicate commercial progress, but they do not necessarily demonstrate that a business is becoming more profitable.
Developing additional products creates costs. Entering new markets requires investment. Securing major retail accounts can involve substantial expenditure, while expanding marketing activity may generate relatively little additional profit if consumer demand does not respond as expected.
There is also a tendency within some businesses to treat sales growth as the solution to almost every financial challenge. When margins come under pressure, the instinctive response can be to seek additional revenue rather than address the underlying economics.
That approach can work when additional sales generate sufficient incremental contribution. However, it becomes dangerous when the business is effectively selling more products without making more money. A smaller product portfolio containing a limited number of highly successful toys can sometimes outperform a much larger range that includes numerous marginally profitable or loss-making products.
Similarly, a manufacturer with a diversified network of profitable customers may be financially healthier than a competitor generating substantially greater revenue through a handful of commercially demanding retail accounts.
The objective should not simply be to become bigger. It should be to become more profitable, more resilient and better positioned to generate sustainable returns on the capital invested in the business.
What Should Toy Companies Be Doing Differently?
There is no universal solution to the industry's margin challenges, but there are several areas where manufacturers can improve their commercial position.
First, businesses need a much clearer understanding of their true product and customer profitability. This means looking beyond factory costs and headline wholesale prices to incorporate development expenditure, promotional funding, logistics and other relevant expenses. Without this information, it becomes extremely difficult to distinguish genuinely profitable business from revenue that merely creates additional activity.
Second, toy companies should become more disciplined about product development and range management. Launching large numbers of new products is expensive, and not every new item deserves to progress from concept to commercial production. More rigorous assessment of potential demand, manufacturing economics and likely retailer support can help reduce unnecessary expenditure.
Third, companies should carefully evaluate the financial attractiveness of their distribution channels. Major retail customers can generate enormous commercial opportunities, but specialist retailers, regional chains, online channels and direct-to-consumer sales may offer different combinations of margin, volume and risk.
Fourth, manufacturers need to pay greater attention to working capital. A profitable product can still create serious financial problems if substantial cash is tied up in inventory for too long. Better forecasting, more efficient production planning and tighter inventory management can make a meaningful difference to business performance.
Finally, businesses should consider whether they have sufficient genuine differentiation to protect their selling prices. Companies competing primarily on price are likely to remain vulnerable to cost inflation and retailer negotiating pressure. Those offering distinctive products, strong brands or meaningful consumer benefits may have greater flexibility to maintain sustainable margins.
None of these measures is particularly revolutionary. However, effective execution can be the difference between a toy company that generates impressive sales figures and one that consistently produces attractive profits.
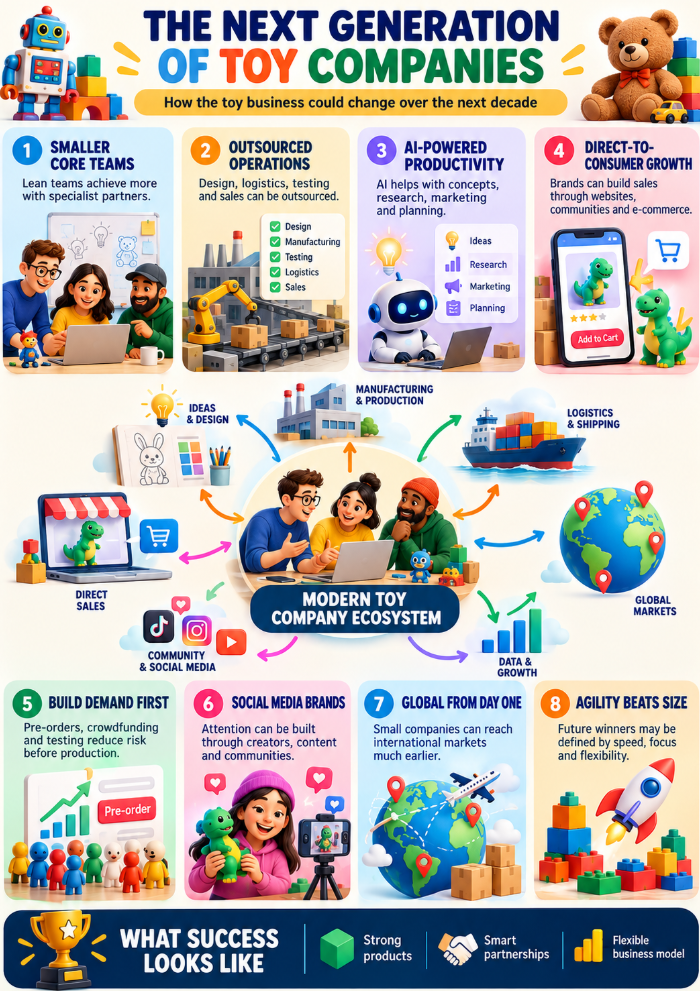
The Future May Belong to Toy Companies That Do Less, but Do It Better
One potentially significant consequence of the current margin squeeze is that it may accelerate changes in the structure of the toy industry itself. Historically, many successful toy companies have pursued growth through expanding product ranges, additional brands, new international markets and increased retail distribution. That approach remains commercially attractive in the right circumstances, but it also creates organisational complexity and financial commitments.
Advances in technology, outsourcing and artificial intelligence may allow the next generation of toy companies to operate with substantially leaner organisational structures. Product development, marketing, administration and certain commercial functions can increasingly be managed through specialist external partners or supported by technology.
A business that once required a relatively substantial internal team may eventually be able to achieve similar commercial outcomes with fewer permanent employees and a more flexible cost structure.
However, reducing overheads is only part of the equation. The most successful companies will also need to become better at selecting commercial opportunities, developing products with genuine consumer appeal and avoiding investments that do not offer sufficient potential returns.
It is entirely possible that some of the most attractive toy businesses of the next decade will not be the companies with the largest product ranges or the biggest sales teams.
They may be the ones with a carefully selected portfolio of successful products, strong intellectual property, efficient operations and a relentless focus on profitability.

Ultimately, Who Wins and Who Loses?
The toy industry's current financial challenges do not mean the sector is fundamentally unattractive. Toys remain an important part of family life, consumer enthusiasm for play continues to evolve, and successful products can generate exceptional commercial returns.
The strong sales performance reported during 2026 demonstrates that demand remains substantial, particularly in categories benefiting from collectibles, licensing, adult consumers and established brands.
However, the financial rewards are unlikely to be distributed evenly. Businesses possessing strong intellectual property, differentiated products, efficient operations and sufficient negotiating power are generally better positioned to protect their profitability. Manufacturers relying on undifferentiated products, expensive licensing arrangements and aggressive discounting may face a much more difficult environment.
Retailers will continue to demand competitive prices, while consumers will ultimately decide whether individual products represent acceptable value. Manufacturers unable to reconcile those expectations with their own rising costs will struggle.
Perhaps the most important lesson is that the toy industry needs to become more disciplined about distinguishing sales growth from genuine financial success. There is nothing inherently impressive about generating $100 million in revenue if the business produces only marginal profits, consumes enormous amounts of working capital and remains constantly exposed to financial risk.
Conversely, a smaller company generating $10 million in annual sales with attractive margins, healthy cash flow and a sustainable competitive position may represent a considerably more successful commercial operation. As costs continue to rise and competition remains intense, this distinction is likely to become increasingly important.
The companies that prosper will not necessarily be those selling the most toys. They will be those that have worked out how to make the most money from the toys they sell.